Tampilkan postingan dengan label Life Insurance. Tampilkan semua postingan

Rabu, 16 Januari 2019

Tentang Harapan yang Tidak Kunjung Nyata, Allah Menyuruhmu Menunggu. Maka Bersabarlah!

Untukmu yang masih saja gelisah akan rencana-Nya, sudahilah rasa gelisahmu, sudahilah rasa getirmu, dan sudahilah dari beripikir yang tidak-tidak tentang harapan yang kamu haturkan kepada Allah.
Berhusnuddzan saja kepada Allah sebanyak-banyaknya, hingga akhirnya hatimu spenuh dengan rasa yakin, bukan rasa getir.
Karena bagaimanapun harapanmu selama ini sudah Allah lihat dengan sempurna, dan tentang ia yang tidak kunjung menjadi nyata, Allah menyuruhmu menunggu. Maka bersabarlah!

Tidak Usah Banyak Protes Tentang Sesuatu yang Masih Saja Samar, Karena Pada Akhirnya Akan Menjadi Nyata Juga


instagram.com/melodyprima
Jalani apa-apa yang telah Allah tuliskan kepadamu, jangan banyak mengeluh, dan tidak usah banyak protes tentang sesuatu yang masih saja samar, karena pada akhirnya harapanmu akan menjadi nyata juga.
Jangan gegabah, hanya karena kamu pikir waktu terbaik telah tiba, sebab sungguh waktu terbaik itu hanya Allah yang tahu, dan kapan ia harus sampai kepadamu.

Bersabarlah Dulu Dalam Rentetan Rencana-Nya, Karena Pada Akhirnya Kamu Akan Menemukan Apa yang Kamu Harapkan


instagram.com/melodyprima
Intinya bersabarlah dulu dalam rentetan rencana-Nya, mungkin bagimu waktu yang kamu jalani sangatlah lama, tapi dibalik itu semua ada rencana indah Allah yang nantinya akan sangat kamu syukuri.
Untuk itu, bersabar dan tetapah bersabar, jangan beri ruang hatimu untuk merutuki apapun yang masih menjadi rahasia-Nya, karena bagaimanapun lamanya kamu menunggu tetap saja pada akhirnya kamu akan menemukan apa yang kamu harapkan.

Allah Tidak Pernah Mengabaikan Keinginan Baikmu, Hanya Saja Allah Menyuruhmu Bersabar Terlebih Dahulu


instagram.com/melodyprima
Dan mudah bagi Allah mengabulkan harapanmu sekarang juga, tapi Allah tidak setega itu memberi takdir yang kamu inginkan sedangkan Dia tahu bahwa semuanya tidak baik untukmu.
Jadi bersabarlah, jalani apa yang Allah persembahkan kepadamu saat ini, jangan banyak mengeluh dan jangan pula banyak bertanya, cukup kamu yakin saja bahwa bila telah tiba waktunya pasti harapanmu akan menjadi nyata dengan sempurna.

Kamu Tidak Pernah Tahu Kapan Waktu Terbaik Dalam Hidupmu, Sebab Itulah Mengapa Seharusnya Kamu Patuh Saja Pada Rencana-Nya


instagram.com/melodyprima
Lagipula kamu tidak pernah tahu kapan waktu terbaik dalam hidupmu, selama ini kamu hanya mengira-ngira saja, sedangkan Allah sangat tahu kapan waktu terbaik tersebut, maka sebab itulah mengapa kamu seharusnya patuh saha pada setiap rencana-Nya.
Yakinlah, karena kamu tidak akan pernah kecewa dengan setiap takdir yang Allah putuskan, bila kamu sudah yakin kepada Allah tiada henti dan selalu sepenuh hati.

Percayalah Semua Akan Indah Pada Waktunya, Bahkan Lebih Indah Dari Apa yang Ada Dalam Benakmu Selama Ini


instagram.com/melodyprima
Lantas bagaimanapun lamanya kamu menunggu keputusan dari Allah tetap percaya saja bahwa bila telah sampai waktu yang Allah rencanakan maka semua akan indah, bahkan akan lebih indah dari apa yang ada dalam benakmu selama ini.
Percaya saja bahwa setelah waktu menunggumu yang lama ini akan hadir kisah indah yang akan membuatmu mengerti bahwa setiap yang Allah rencanakan pasti berakhir dengan kebaikan yang nyata.
cccccccc

Senin, 24 September 2018

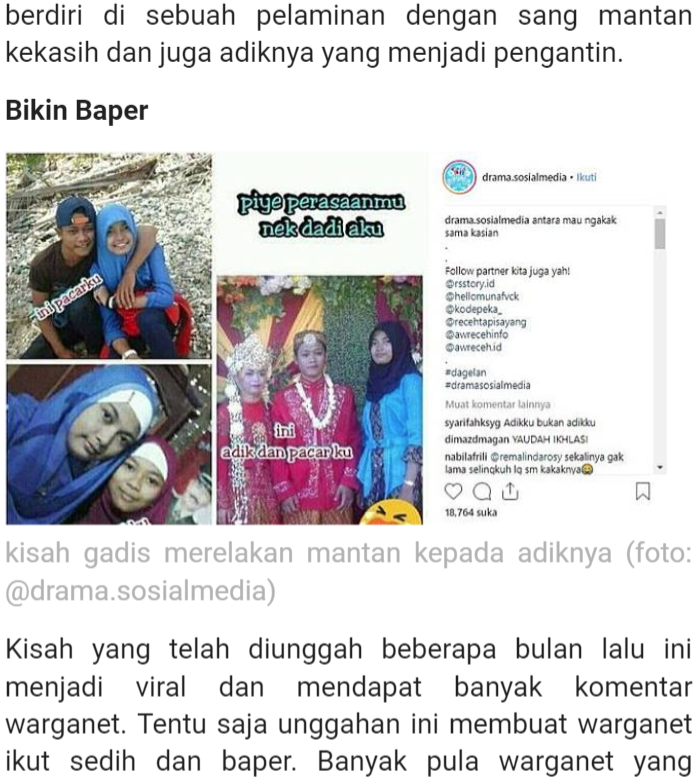
Ngenes, Wanita Ini Relakan Mantan Pacar Nikahi Adiknya


life cover
insure
insurance agent
general insurance
public liability insurance
sbi life insurance
life insurance
what is life insurance
reliance life insurance
life insurance policy
term life insurance
pacific life insurance
whole life insurance
state farm insurance
allstate insurance
medical insurance
best life insurance
health insurance california
life insurance corporation
health insurance texas
cheap health insurance
group health insurance
health insurance coverage
small business health insurance
business health insurance
compare health insurance
the personal insurance
travel health insurance
health insurance companies
best health insurance
insurance agents
car insurance quotes
health insurance quotes
aetna health insurance
individual health insurance
private health insurance
health insurance agent
insurance premium
landlord insurance
cheap auto insurance
best life insurance companies
online auto insurance
insurance quotes online
liability insurance
life insurance australia
income protection insurance
property insurance
product liability insurance
mortgage insurance
healthcare insurance
cigna health insurance
home insurance
best insurance
insurance quotes
term insurance
compare insurance
insurance
american insurance
car insurance uk
dental insurance


A life insurance is an effective tool to protect oneself and their family against any kind of eventuality that may occur. Various leading providers of life insurance products are Aviva Life Insurance, SBI Life Insurance, Kotak Life Insurance, and so on.


In life, most of the decisions that we take are based on thorough research and analysis. Then why is it, that when it comes to life insurance we make decisions only at the time of paying tax? Tax saving is an important and value added benefit that life insurance provides to us. However, the main objective of these is to secure the future of the individual’s family in case of the death of the person. A life insurance is one of the many savings, whose benefits that people avail, mainly during the tax season. It has been listed under Section 80C of the Income Tax Act in the constitution. Investments up to Rs. 1 lakh are eligible for deductions under this section.

Aviva Life Insurance: There are many private funding firms that provide life insurance to individuals. One of these is Aviva Life Insurance. It provides a wide range of protection plans for its customers. There include Aviva LifeShield, Aviva LifeShield Plus, Aviva i-Life, and so on. Each insurance product comes with various added features, riders and benefits. For example, the Aviva LifeShield Plus provides riders as a means of protection during medical problems; Aviva LifeShield Advantage provides not only an insurance plan but also an additional protection against any kind of disability due to an accident, maturity benefits on completion of the insurance cover, and health riders, and so on. All these products provide wide possibilities to save tax and also secure your family’s and own future.

SBI Life Insurance: One of the leading public sector banks of India or SBI is a leading provider of life insurance products, under the name of SBI Life Insurance. Just like any other dealer of life insurance, SBI also has a large catalogue of life insurance products. They provide SBI Life e-Shield, SBI Life – SmartIncomeShield, SBI Life – Saral Shield, SBI Life – Smart Shield, and so on. All of these protection plans are term plans which provide a varied list of advantage. One of these, SBI SmartIncomeShield provides a pure term insurance plan and helps you secure the future of your family against death, life – threatening illness or even disability.

The customer is given a wide range of choices from which they can select a Term Life Insurance, whichever is suitable for them.

There are many other leading banks and insurance companies that provide the client with an option to avail life insurance online. All of the leading insurance providers have their own active web portal online from where the prospective client can compareFree Reprint Articles, apply online and get the insurance approved.


cccccccc

Cinderella Story asal Indonesia Ini Bikin Baper, Ketika Seorang Manager Jatuh Hati dengan Babysitter


life cover
insure
insurance agent
general insurance
public liability insurance
sbi life insurance
life insurance
what is life insurance
reliance life insurance
life insurance policy
term life insurance
pacific life insurance
whole life insurance
state farm insurance
allstate insurance
medical insurance
best life insurance
health insurance california
life insurance corporation
health insurance texas
cheap health insurance
group health insurance
health insurance coverage
small business health insurance
business health insurance
compare health insurance
the personal insurance
travel health insurance
health insurance companies
best health insurance
insurance agents
car insurance quotes
health insurance quotes
aetna health insurance
individual health insurance
private health insurance
health insurance agent
insurance premium
landlord insurance
cheap auto insurance
best life insurance companies
online auto insurance
insurance quotes online
liability insurance
life insurance australia
income protection insurance
property insurance
product liability insurance
mortgage insurance
healthcare insurance
cigna health insurance
home insurance
best insurance
insurance quotes
term insurance
compare insurance
insurance
american insurance
car insurance uk
dental insurance


Term Life by definition is a life insurance policy which provides a stated benefit upon the holder's death, provided that the death occurs within a certain specified time period. However, the policy does not provide any returns beyond the stated benefit, unlike an insurance policy which allows investors to share in returns from the insurance company's investment portfolio.

Annually renewable term life.

Historically, a term life rate increased each year as the risk of death became greater. While unpopular, this type of life policy is still available and is commonly referred to as annually renewable term life (ART).

Guaranteed level term life.

Many companies now also offer level term life. This type of insurance policy has premiums that are designed to remain level for a period of 5, 10, 15, 20, 25 or even 30 years. Level term life policies have become extremely popular because they are very inexpensive and can provide relatively long term coverage. But, be careful! Most level term life insurance policies contain a guarantee of level premiums. However some policies don't provide such guarantees. Without a guarantee, the insurance company can surprise you by raising your life insurance rate, even during the time in which you expected your premiums to remain level. Needless to say, it is important to make sure that you understand the terms of any life insurance policy you are considering.
Return of premium term life insurance

Return of premium term insurance (ROP) is a relatively new type of insurance policy that offers a guaranteed refund of the life insurance premiums at the end of the term period assuming the insured is still living. This type of term life insurance policy is a bit more expensive than regular term life insurance, but the premiums are designed to remain level. These returns of premium term life insurance policies are available in 15, 20, or 30-year term versions. Consumer interest in these plans has continued to grow each year, as they are often significantly less expensive than permanent types of life insurance, yet, like many permanent plans, they still may offer cash surrender values if the insured doesn't die.

Types of Permanent Life Insurance Policies

A permanent life insurance policy by definition is a policy that provides life insurance coverage throughout the insured's lifetime ñ the policy never ends as long as the premiums are paid. In addition, a permanent life insurance policy provides a savings element that builds cash value.
Universal Life

Life insurance which combines the low-cost protection of term life with a savings component that is invested in a tax-deferred account, the cash value of which may be available for a loan to the policyholder. Universal life was created to provide more flexibility than whole life by allowing the holder to shift money between the insurance and savings components of the policy. Additionally, the inner workings of the investment process are openly displayed to the holder, whereas details of whole life investments tend to be quite scarce. Premiums, which are variable, are broken down by the insurance company into insurance and savings. Therefore, the holder can adjust the proportions of the policy based on external conditions. If the savings are earning a poor return, they can be used to pay the premiums instead of injecting more money. If the holder remains insurable, more of the premium can be applied to insurance, increasing the death benefit. Unlike with whole life, the cash value investments grow at a variable rate that is adjusted monthly. There is usually a minimum rate of return. These changes to the interest scheme allow the holder to take advantage of rising interest rates. The danger is that falling interest rates may cause premiums to increase and even cause the policy to lapse if interest can no longer pay a portion of the insurance costs.

To age 100 level guaranteed life insurance

This type of life policy offers a guaranteed level premium to age 100, along with a guaranteed level death benefit to age 100. Most often, this is accomplished within a Universal Life policy, with the addition of a feature commonly known as a "no-lapse rider". Some, but not all, of these plans also include an "extension of maturity" feature, which provides that if the insured lives to age 100, having paid the "no-lapse" premiums each year, the full face amount of coverage will continue on a guaranteed basis at no charge thereafter.

Survivorship or 2nd-to-die life insurance

A survivorship life policy, also called 2nd-to-die life, is a type of coverage that is generally offered either as universal or whole life and pays a death benefit at the later death of two insured individuals, usually a husband and wife. It has become extremely popular with wealthy individuals since the mid-1980's as a method of discounting their inevitable future estate tax liabilities which can, in effect, confiscate an amount to over half of a family's entire net worth!

Congress instituted an unlimited marital deduction in 1981. As a result, most individuals arrange their affairs in a manner such that they delay the payment of any estate taxes until the second insured's death. A "2nd-to-die" life policy allows the insurance company to delay the payment of the death benefit until the second insured's death, thereby creating the necessary dollars to pay the taxes exactly when they are needed! This coverage is widely used because it is generally much less expensive than individual permanent life coverage on either spouse.

Variable Universal Life

A form of whole life which combines some features of universal life, such as premium and death benefit flexibility, with some features of variable life, such as more investment choices. Variable universal life adds to the flexibility of universal life by allowing the holder to choose among investment vehicles for the savings portion of the account. The differences between this arrangement and investing individually are the tax advantages and fees that accompany the insurance policy.

Whole Life

Insurance which provides coverage for an individual's whole life, rather than a specified term. A savings component, called cash value or loan value, builds over time and can be used for wealth accumulation. Whole life is the most basic form of cash value insurance. The insurance company essentially makes all of the decisions regarding the policy. Regular premiums both pay insurance costs and cause equity to accrue in a savings account. A fixed death benefit is paid to the beneficiary along with the balance of the savings account. Premiums are fixed throughout the life of the policy even though the breakdown between insurance and savings swings toward the insurance over time. Management fees also eat up a portion of the premiums. The insurance company will invest money primarily in fixed-income securities, meaning that the savings investment will be subject to interest rate and inflation risk.

Life Carrier Direct was founded by managing partners with over 70 years of combined Life Insurance experience. Most people want life insurance to protect the ones they love from any unexpected death so that they will be protected financially to cover such things as loss of household income, funding for education, mortgage satisfaction, and other important financial considerations related to the sanctity of the family. Please visit [http://www.lifecarrierdirect.com] for a quote comparison of all the major A rated life insurance carriers.


Article Source: http://EzineArticles.com/5219876


cccccccc

Tak Mau Ada Korban Lagi, Ibu ini Bagikan Kisah Haru Anaknya Terbaring Lemah


life cover
insure
insurance agent
general insurance
public liability insurance
sbi life insurance
life insurance
what is life insurance
reliance life insurance
life insurance policy
term life insurance
pacific life insurance
whole life insurance
state farm insurance
allstate insurance
medical insurance
best life insurance
health insurance california
life insurance corporation
health insurance texas
cheap health insurance
group health insurance
health insurance coverage
small business health insurance
business health insurance
compare health insurance
the personal insurance
travel health insurance
health insurance companies
best health insurance
insurance agents
car insurance quotes
health insurance quotes
aetna health insurance
individual health insurance
private health insurance
health insurance agent
insurance premium
landlord insurance
cheap auto insurance
best life insurance companies
online auto insurance
insurance quotes online
liability insurance
life insurance australia
income protection insurance
property insurance
product liability insurance
mortgage insurance
healthcare insurance
cigna health insurance
home insurance
best insurance
insurance quotes
term insurance
compare insurance
insurance
american insurance
car insurance uk
dental insurance


The primary purpose for getting life insurance will always be to protect the people you care about in case something were to happen to you. How much capital would you need in order to pay off debts, support your loved ones, or to take care of all your affairs?

After you understand what priorities you would like to protect through life insurance it is fairly easy to determine the correct amount of coverage.

What Type Of Life Insurance

The next question is what type of coverage will best serve your needs. In order to get the right amount of coverage you also have to make sure that the premiums fit comfortably into your budget.

Term Insurance Benefits

Term insurance is less expensive than whole life insurance, because you are renting the insurance. Your coverage is considered pure insurance in this case, because it doesn't develop cash value or participate in company dividends.

Instead it allows you to get the right amount of protection for the least expensive premiums available. Term insurance has also developed over the years to offer more comprehensive options. You can get a return-of-premiums policy where you pay more during the life of the policy, but the insurance company refunds all of your premiums at the end of the fixed term.

There are also term policies that allow you to lock in your age and health for the remainder of your life, so that you can have the coverage and premiums locked in for the rest of your life. This is a great and inexpensive way to obtain permanent insurance.

How Long Should You Lock In Your Premiums

The longer you can lock in your premiums the more advantageous it will be in the long run. The insurance company takes into consideration the mortality risk during the level period of the term. If you are 35 and you get a level 20-term policy then the rates will be fixed until you are 55. And because you are locking in the premiums at a younger age, the average risk and rates will be less than if you were to lock in your premiums at 55.

Most people have an insurance need that will last throughout the rest of their lives. If you can permanently lock in a portion of your insurance at a younger age this can save you substantially on premiums. It happens quite often where people will have to apply for new coverage after the fixed rates on their current policy have expired, and because they are now older and have to pay much more in premiums.

Your health is also locked in when you first take the policy out. Many people looking for insurance in their fifties or sixties are dealing with some type of medical condition that makes the cost of life insurance double or triple in cost. The same logic that applies to locking in your age is also good to keep in mind when locking in your health. We don't know what is going to happen to us, and if we have our insurance locked in then our insurability and premiums will be unaffected by a medical event.

Level Term Insurance

I always recommend getting a level-term policy as opposed to one that will start off lower and increase premiums each and every year. The level term policies allow you to lock in your age and health for the remainder of the term, whereas the increasing-premium policies become more expensive every year based on your new age.

Because term insurance is a less expensive way to get the right amount of protection, I believe that it is the right choice for a large majority of people looking at life insurance.

Cash Value Life Insurance: When To Consider It

First A Word Of Caution About How The Life Insurance Industry Operates

An agent who pushes one company above the others is doing his or her clients a disservice. Every company has its positives and negatives and each company has focused on certain demographics to try to create a competitive edge. There are 17 life insurance companies in the fortune 500 alone. These companies have very similar investment portfolios and conduct business in ways that are more common than not. Eight of these companies are mutual, nine are stock companies, and they all operate in order to make a profit. The most important thing that anybody can do is to have an agent who can help them shop the market for the company that is going to fit their needs best. Somebody that is a smoker with high blood pressure is going to have better options outside of the companies that target nonsmokers without health conditions. Finding the least expensive company on the market for your age and health can save you thousands of dollars.

I used to work for an insurance agency where we only sold a single triple-A-rated-insurance company. When I worked for this agency, my fellow agents and I were especially inculcated with the benefits of this company's whole life insurance. This situation is not unique.

Captive agencies have managers that groom agents to push one company because they get paid commissions when their agents sell these products. Please don't assume that life insurance agents are experts on the benefits of different companies and types of insurance plans, because many of them are unaware of the benefits beyond their own company. Instead of consulting their clients and shopping the market they push a single product that doesn't always match up well. There are far too many people being given advice from agents to consider whole life insurance, because they are trained to present the same products to every client.

When You Are Considering An Insurance Company It Will Always Be Advantageous For Some People And Ill Advised For Others

If you sit down with an agent who goes over a list of benefits about a single insurance company, keep in mind that most benefits are really trade-offs. For instance, if a company is a triple-A rated insurance company than they are probably also more conservative with whom they insure. A triple-A rating is great, but it is really only necessary if you plan on participating in the companies dividends, or in other words buying their whole life insurance. There is no need to pay extra money for the privilege of having a triple-A rated company as many agents insist. A.M. Best considers a company with an A-rating to be in excellent financial health and there are many A-rated companies with less expensive insurance offers if you are not planning on participating in whole life.

When Whole Life Insurance is a Good Idea

For some people, whole life insurance can be a great complement to their financial security. I have sold whole life insurance based on the following benefits.
1) It has a guaranteed return that will consistently build up the cash value in the policy.
2) It gives policyholders permanent insurance so that they are insured throughout their lifetime.
3) It allows them to stop paying premiums after a certain number of years, because the dividends from the company will be enough to keep the policy in force.
4) It allows policyholders to take cash from the policy in the form of a loan, so that you have another option if liquidity is needed.
5) The growth of the policy is tax deferred and tax-free as long as long as the policy is kept in force.

The problem can be that many of these benefits point to life insurance as an asset or investment. Life insurance should always be considered for the death benefit first and foremost. If you have already maxed out both your Roth Ira and 401(k), have at least three months of expenses in accessible savings, and are looking for something else to build up savings then whole-life insurance can be a good option. The point is that whole life insurance is a good choice when you have the ability to max out your qualified retirement funds and are looking to complement your savings with a conservative tie in to your life insurance.

Whole life can be a mistake for a couple of reasons

There are risks when putting your money into whole life insurance. The risks aren't always clearly explained, because the agents focus on the guaranteed dividends that will grow the cash value every year. However, one significant risk is buying into whole-life insurance, paying the premiums for a number of years, and then not being able to keep up with the premiums down the road. Life insurance companies bank on this happening to a certain percentage of policyholders.
If this occurs you are in danger of losing thousands of dollars in paid premiums without the benefit of accumulating any cash value. When a policy lapses or you can't keep up with whole life premiums then the insurance company will retain your premiums without you having any cash value built up or any insurance in force.
These whole life polices are structured to have large front end expenses and it will take at least a couple of years before your premiums start to build up cash value. It takes about ten years before the amount of premiums you put into the policy will equal the cash value in the policy.

How Cash Value In Whole Life Insurance Works

The other risk with whole life insurance is not understanding how the cash value in the policy works and taking out too much of it. The cash value in the policy is liquid, but the insurance company will let you take out about 97% of it in order to protect against the policy lapsing. Any cash that is taken out of the policy is loaned from the policy at interest.

Lets assume that you are in the first 20 years of your whole life policy and are taking a loan from the cash value in the policy. The loaned interest rate is 8.0 %, the non-loaned dividend interest rate is 6.85%, and the loaned-dividend interest is rate is 7.9 %. Notice that the insurance company steps up the interest rate on the loaned amount or the amount borrowed from your cash value. This mitigates the cost of the loan, but the loan still creates an ongoing obligation to pay interest. For instance the cost of borrowing here would be 6.95 %.

(The loaned interest rate (8.0 %) + (the non-loaned dividend interest rate (6.85%) - the loaned-dividend interest rate (7.9%)) = cost of borrowing (6.95%).

The cash value in the policy is really a double-edged sword, because it leads to a significant risk that you will not be able to keep up with the premiums. It is practically intended for people who can repay the loan quickly so that the policy continues to develop dividends instead of an obligation to pay interest. It is great for people who aren't ever tempted to borrow from the policy, because the dividends will compound and eventually be able to cover the cost of annual premiums. When this occurs the risk of lapsing will be negligible. However, this takes quite some time to achieve and it truly depends on how disciplined you can afford to be with the additional cost of these premiums. If you would rather have control of your money up front there is an argument that you can buy term and invest the rest instead of leveraging the insurance companies general fund.

Your Personality Profile And Budget Must Be In Line

I recommend taking a look at both your budget and how much control you want over your money for at least the next ten years if you are considering whole life. Because term insurance can now permanently lock in your age and health in the same manner as whole life insurance, the biggest question is whether or not you want control over investing the difference in premiums. Many people prefer whole life insurance because they don't have to think about investing the difference; the insurance company does it for them. They can also grow their death benefit by the amount of growth in cash value and act as their own creditor if they ever want to borrow cash from the policy.

A Couple Other Points About Whole Life Insurance

The cash value component in a whole life insurance policy needs to be addressed. The first is that cash value is based on compounding dividends. So the longer you keep the paying premiums the more advantageous it is. The second is that if you go with a reliable insurance company they will usually pay non-guaranteed dividends that are based on the results of an insurance companies investments. This is when rating is important to consider, because you are now participating in these dividends. Also if you have allowed the cash value to grow and take out modest loans from the policy later in life, you will most likely have enough in dividends to keep pace beyond the ongoing obligation of interest. However if you do surrender the policy the gains will be taxed as capital gains and you will have to pay a surrender charge as well. If the policy is in force and you pass away while there are still outstanding loans, the death benefit will be paid out after it covers the cost of the loans that you have taken from the policy.

Term Insurance Vs. Whole Life

I believe the most important factor in all of this is the human element. If you are patient, conservative, and comfortably able to continue paying premiums without the temptation to borrow from the cash-value then you are a good candidate for whole life insurance. The majority of people have fluctuating budgets and circumstances where they are better off with something that locks in their age and health and gives them the opportunity to invest the difference elsewhere.

If you are looking to find the right type of insurance look no further. I am a licensed agent, business owner, and financial author and my goal is to consult people on the best options available in the life insurance market. I am licensed in over ten states and have helped thousands of people find a policy based on their priorities and saving them money. To get a free online quote go to:

[http://www.cheapinsurancedirectory.com/]

Or if you would like to speak to me and have me personally shop the market for the guaranteed-cheapest insurance available call 1-888-611-2688. I will talk to you about your priorities and give you a FREE-NO-OBLIGATION REPORT on the least expensive insurance for your age, health, and circumstances. If you are satisfied with report's results the process of insuring your family can all be done online or over the phone to save you time as well. Please call me now at 1-888-611-2688 and I will work to save you thousands of dollars on your life insurance!


Article Source: http://EzineArticles.com/7165008


cccccccc

Hanya Butuh 1 Menit, Lakukan Gerakan Mudah Ini di Rumah, Manfaatnya Bisa Mengecilkan Perut Buncit yang Menggelambir!


life cover
insure
insurance agent
general insurance
public liability insurance
sbi life insurance
life insurance
what is life insurance
reliance life insurance
life insurance policy
term life insurance
pacific life insurance
whole life insurance
state farm insurance
allstate insurance
medical insurance
best life insurance
health insurance california
life insurance corporation
health insurance texas
cheap health insurance
group health insurance
health insurance coverage
small business health insurance
business health insurance
compare health insurance
the personal insurance
travel health insurance
health insurance companies
best health insurance
insurance agents
car insurance quotes
health insurance quotes
aetna health insurance
individual health insurance
private health insurance
health insurance agent
insurance premium
landlord insurance
cheap auto insurance
best life insurance companies
online auto insurance
insurance quotes online
liability insurance
life insurance australia
income protection insurance
property insurance
product liability insurance
mortgage insurance
healthcare insurance
cigna health insurance
home insurance
best insurance
insurance quotes
term insurance
compare insurance
insurance
american insurance
car insurance uk
dental insurance

Are you considering or being pressured to buy life insurance? Join the crowd. Life insurance is one of the most ubiquitous financial products to ever be sold. While life insurance can be a valuable tool in any financial plan, knowing if you even need it -- along with the right amount and type to buy -- can be challenging. There are questions such as: How do I know if I need life insurance? If so, how much life insurance do I need? What type of policy should I buy? How do I know if I am getting the best value and price for the life insurance I buy?

Purchasing life insurance is often tedious, intimidating and complicated, but it does not have to be that way. The insurance companies may offer multiple confusing policies and throw around a lot of jargon that sounds like a foreign language, but in reality, the concepts are simple. Once you understand the true basics of life insurance, your decision can be straightforward and result in the best buy for you.

What you should know about life insurance:

The purpose of life insurance (and, really, its only value) is to offset the economic cost of dying. If you have a spouse or young children who would be faced with financial hardship in the event of your death, life insurance proceeds can solve that problem. If you are a key person or partner in a business, life insurance can help to stabilize the business in the event of your death.


If insurance companies try to convince you that a life insurance policy is anything other than a way to replace your income or long-term economic value to a family or business in the event of your death, they are doing so for their benefit, not yours. Life insurance is not an investment -- it is not a way to make money or an effective tax hedge.

There is an uncomplicated way to decide if you even need life insurance. Ask yourself: If I die, will anyone I care about suffer an economic adversity that I want to prevent? If the answer is no, then you don’t need life insurance. If, however, you want to protect others from the potential economic cost of your death, the right type of life insurance is the best way to accomplish that objective.
If you need life insurance, what type should you buy?

Life insurance companies have more confusing policy options than a Chinese restaurant. But when it comes down to it, all insurance companies pine to sell you some form of what they call “whole life” or “permanent insurance.” (Both are subtle marketing terms used to suggest you should buy and keep paying premiums on the policy for your whole life.) This type of policy has been the backbone, best selling and most profitable product of the life insurance industry for years. So-called “whole life” may have been a reasonable option in the 20th century when the consumer had few other financial options, but that is not the case today.

The supposed benefit for the buyer of whole life is that premiums will never rise and, over time, a certain amount of “cash value” will accumulate in the policy. The truth is that whole life is more like an annuity for insurance companies than a benefit for policyholders. What makes the product so profitable for the insurance company is that, when the insured is young (and least likely to die), the premium charged is hundreds of times higher than the actual cost to provide the promised death benefit. The insurance company invests the excess premium and keeps the profits for itself. Insurance companies know that, by the time the insured ages and is more likely to die, over 97% of the policies will have been canceled with no death benefit paid. That is a good deal, if you are an insurance company but not so good for someone who pays inflated premiums for years and turns out not to need the insurance.

If you do need life insurance, the best way to meet that need is to buy it on a temporary basis for a specific term. For example, your children are not going to be young forever, so why buy life insurance that will last forever? The fact is that your needs will change over time, so you should own insurance that could change as well.

Thus, the most efficient approach to buying life insurance is on a temporary (term) basis. These could be for periods of 5 or 10 years each. These policies only pay a death benefit, but they are significantly less expensive. The policies can be guaranteed to be renewed (no matter how your health may change) at the end of each period (with slightly increased premiums) until you are well into your 80s. This approach -- at less cost -- allows you to review your life insurance needs at the end of each period and decide if you still need the same amount of coverage.

How To Buy Life Insurance (If You Need It)

Life insurance has become much like a commodity, so you should buy it like a commodity. That is, all policies offered by all companies -- especially the renewable, temporary type -- are essentially identical, so it is best to shop around, compare premiums and buy the cheapest one.

That does not mean you have to take the time to talk with 5 or 10 different companies in order to shop. There any number of websites that have relationships with numerous companies, and these sites can provide a spreadsheet of multiple companies offering totally identical policies. This will allow you to easily compare premiums -- which, surprisingly, will be different. It’s a little like shopping online for the cheapest ticket offered by airlines all going to the same place.

In the end, life insurance can be a simple and survivable process. The key is to make sure that you are in charge -- not the insurance company.


cccccccc

Selingkuhan Telepon Suami, "Ketauan" Sama Istri! Siapa Sangka "Ini" Cara Sang Istri Mempermalukan Mereka!


life cover
insure
insurance agent
general insurance
public liability insurance
sbi life insurance
life insurance
what is life insurance
reliance life insurance
life insurance policy
term life insurance
pacific life insurance
whole life insurance
state farm insurance
allstate insurance
medical insurance
best life insurance
health insurance california
life insurance corporation
health insurance texas
cheap health insurance
group health insurance
health insurance coverage
small business health insurance
business health insurance
compare health insurance
the personal insurance
travel health insurance
health insurance companies
best health insurance
insurance agents
car insurance quotes
health insurance quotes
aetna health insurance
individual health insurance
private health insurance
health insurance agent
insurance premium
landlord insurance
cheap auto insurance
best life insurance companies
online auto insurance
insurance quotes online
liability insurance
life insurance australia
income protection insurance
property insurance
product liability insurance
mortgage insurance
healthcare insurance
cigna health insurance
home insurance
best insurance
insurance quotes
term insurance
compare insurance
insurance
american insurance
car insurance uk
dental insurance


Life insurance is one of the most important components of any individual's financial plan. However there is lot of misunderstanding about life insurance, mainly due to the way life insurance products have been sold over the years in India. We have discussed some common mistakes insurance buyers should avoid when buying insurance policies.

1. Underestimating insurance requirement: Many life insurance buyers choose their insurance covers or sum assured, based on the plans their agents want to sell and how much premium they can afford. This a wrong approach. Your insurance requirement is a function of your financial situation, and has nothing do with what products are available. Many insurance buyers use thumb rules like 10 times annual income for cover. Some financial advisers say that a cover of 10 times your annual income is adequate because it gives your family 10 years worth of income, when you are gone. But this is not always correct. Suppose, you have 20 year mortgage or home loan. How will your family pay the EMIs after 10 years, when most of the loan is still outstanding? Suppose you have very young children. Your family will run out of income, when your children need it the most, e.g. for their higher education. Insurance buyers need to consider several factors in deciding how much insurance cover is adequate for them.

· Repayment of the entire outstanding debt (e.g. home loan, car loan etc.) of the policy holder

· After debt repayment, the cover or sum assured should have surplus funds to generate enough monthly income to cover all the living expenses of the dependents of the policy holder, factoring in inflation

· After debt repayment and generating monthly income, the sum assured should also be adequate to meet future obligations of the policy holder, like children's education, marriage etc.

2. Choosing the cheapest policy: Many insurance buyers like to buy policies that are cheaper. This is another serious mistake. A cheap policy is no good, if the insurance company for some reason or another cannot fulfil the claim in the event of an untimely death. Even if the insurer fulfils the claim, if it takes a very long time to fulfil the claim it is certainly not a desirable situation for family of the insured to be in. You should look at metrics like Claims Settlement Ratio and Duration wise settlement of death claims of different life insurance companies, to select an insurer, that will honour its obligation in fulfilling your claim in a timely manner, should such an unfortunate situation arise. Data on these metrics for all the insurance companies in India is available in the IRDA annual report (on the IRDA website). You should also check claim settlement reviews online and only then choose a company that has a good track record of settling claims.

3. Treating life insurance as an investment and buying the wrong plan: The common misconception about life insurance is that, it is also as a good investment or retirement planning solution. This misconception is largely due to some insurance agents who like to sell expensive policies to earn high commissions. If you compare returns from life insurance to other investment options, it simply does not make sense as an investment. If you are a young investor with a long time horizon, equity is the best wealth creation instrument. Over a 20 year time horizon, investment in equity funds through SIP will result in a corpus that is at least three or four times the maturity amount of life insurance plan with a 20 year term, with the same investment. Life insurance should always been seen as protection for your family, in the event of an untimely death. Investment should be a completely separate consideration. Even though insurance companies sell Unit Linked Insurance Plans (ULIPs) as attractive investment products, for your own evaluation you should separate the insurance component and investment component and pay careful attention to what portion of your premium actually gets allocated to investments. In the early years of a ULIP policy, only a small amount goes to buying units.

A good financial planner will always advise you to buy term insurance plan. A term plan is the purest form of insurance and is a straightforward protection policy. The premium of term insurance plans is much less than other types of insurance plans, and it leaves the policy holders with a much larger investible surplus that they can invest in investment products like mutual funds that give much higher returns in the long term, compared to endowment or money back plans. If you are a term insurance policy holder, under some specific situations, you may opt for other types of insurance (e.g. ULIP, endowment or money back plans), in addition to your term policy, for your specific financial needs.

4. Buying insurance for the purpose of tax planning: For many years agents have inveigled their clients into buying insurance plans to save tax under Section 80C of the Income Tax Act. Investors should realize that insurance is probably the worst tax saving investment. Return from insurance plans is in the range of 5 - 6%, whereas Public Provident Fund, another 80C investment, gives close to 9% risk free and tax free returns. Equity Linked Saving Schemes, another 80C investment, gives much higher tax free returns over the long term. Further, returns from insurance plans may not be entirely tax free. If the premiums exceed 20% of sum assured, then to that extent the maturity proceeds are taxable. As discussed earlier, the most important thing to note about life insurance is that objective is to provide life cover, not to generate the best investment return.

5. Surrendering life insurance policy or withdrawing from it before maturity: This is a serious mistake and compromises the financial security of your family in the event of an unfortunate incident. Life Insurance should not be touched until the unfortunate death of the insured occurs. Some policy holders surrender their policy to meet an urgent financial need, with the hope of buying a new policy when their financial situation improves. Such policy holders need to remember two things. First, mortality is not in anyone's control. That is why we buy life insurance in the first place. Second, life insurance gets very expensive as the insurance buyer gets older. Your financial plan should provide for contingency funds to meet any unexpected urgent expense or provide liquidity for a period of time in the event of a financial distress.

6. Insurance is a one-time exercise: I am reminded of an old motorcycle advertisement on television, which had the punch line, "Fill it, shut it, forget it". Some insurance buyers have the same philosophy towards life insurance. Once they buy adequate cover in a good life insurance plan from a reputed company, they assume that their life insurance needs are taken care of forever. This is a mistake. Financial situation of insurance buyers change with time. Compare your current income with your income ten years back. Hasn't your income grown several times? Your lifestyle would also have improved significantly. If you bought a life insurance plan ten years ago based on your income back then, the sum assured will not be enough to meet your family's current lifestyle and needs, in the unfortunate event of your untimely death. Therefore you should buy an additional term plan to cover that risk. Life Insurance needs have to be re-evaluated at a regular frequency and any additional sum assured if required, should be bought.

Conclusion

Investors should avoid these common mistakes when buying insurance policies. Life insurance is one of the most important components of any individual's financial plan. Therefore, thoughtful consideration must be devoted to life insurance. Insurance buyers should exercise prudence against questionable selling practised in the life insurance industry. It is always beneficial to engage a financial planner who looks at your entire portfolio of investments and insurance on a holistic basis, so that you can take the best decision with regards to both life insurance and investments.


cccccccc

Suami Ini Membentak Sang Istri Karena Tak Becus Urus Pekerjaan Rumah, Namun “Sebuah Kalimat” Membuat Ia Merasa Tertampar dan Merasa Bersalah!


life cover
insure
insurance agent
general insurance
public liability insurance
sbi life insurance
life insurance
what is life insurance
reliance life insurance
life insurance policy
term life insurance
pacific life insurance
whole life insurance
state farm insurance
allstate insurance
medical insurance
best life insurance
health insurance california
life insurance corporation
health insurance texas
cheap health insurance
group health insurance
health insurance coverage
small business health insurance
business health insurance
compare health insurance
the personal insurance
travel health insurance
health insurance companies
best health insurance
insurance agents
car insurance quotes
health insurance quotes
aetna health insurance
individual health insurance
private health insurance
health insurance agent
insurance premium
landlord insurance
cheap auto insurance
best life insurance companies
online auto insurance
insurance quotes online
liability insurance
life insurance australia
income protection insurance
property insurance
product liability insurance
mortgage insurance
healthcare insurance
cigna health insurance
home insurance
best insurance
insurance quotes
term insurance
compare insurance
insurance
american insurance
car insurance uk
dental insurance


A lot of people have been approached about using life insurance as an investment tool. Do you believe that life insurance is an asset or a liability? I will discuss life insurance which I think is one of the best ways to protect your family. Do you buy term insurance or permanent insurance is the main question that people should consider?

Many people choose term insurance because it is the cheapest and provides the most coverage for a stated period of time such as 5, 10, 15, 20 or 30 years. People are living longer so term insurance may not always be the best investment for everyone. If a person selects the 30 year term option they have the longest period of coverage but that would not be the best for a person in their 20's because if a 25 year old selects the 30 year term policy then at age 55 the term would end. When the person who is 55 years old and is still in great health but still needs life insurance the cost of insurance for a 55 year old can get extremely expensive. Do you buy term and invest the difference? If you are a disciplined investor this could work for you but is it the best way to pass assets to your heirs tax free? If a person dies during the 30 year term period then the beneficiaries would get the face amount tax free. If your investments other than life insurance are passed to beneficiaries, in most cases, the investments will not pass tax free to the beneficiaries. Term insurance is considered temporary insurance and can be beneficial when a person is starting out life. Many term policies have a conversion to a permanent policy if the insured feels the need in the near future,

The next type of policy is whole life insurance. As the policy states it is good for your whole life usually until age 100. This type of policy is being phased out of many life insurance companies. The whole life insurance policy is called permanent life insurance because as long as the premiums are paid the insured will have life insurance until age 100. These policies are the highest priced life insurance policies but they have a guaranteed cash values. When the whole life policy accumulates over time it builds cash value that can be borrowed by the owner. The whole life policy can have substantial cash value after a period of 15 to 20 years and many investors have taken notice of this. After a period of time, (20 years usually), the life whole insurance policy can become paid up which means you now have insurance and don't have to pay anymore and the cash value continues to build. This is a unique part of the whole life policy that other types of insurance cannot be designed to perform. Life insurance should not be sold because of the cash value accumulation but in periods of extreme monetary needs you don't need to borrow from a third party because you can borrow from your life insurance policy in case of an emergency.

In the late 80's and 90's insurance companies sold products called universal life insurance policies which were supposed to provide life insurance for your whole life. The reality is that these types of insurance policies were poorly designed and many lapsed because as interest rates lowered the policies didn't perform well and clients were forced to send additional premiums or the policy lapsed. The universal life policies were a hybrid of term insurance and whole life insurance policies. Some of those policies were tied to the stock market and were called variable universal life insurance policies. My thoughts are variable policies should only be purchased by investors who have a high risk tolerance. When the stock market goes down the policy owner can lose big and be forced to send in additional premiums to cover the losses or your policy would lapse or terminate.

The design of the universal life policy has had a major change for the better in the current years. Universal life policies are permanent policy which range in ages as high as age 120. Many life insurance providers now sell mainly term and universal life policies. Universal life policies now have a target premium which has a guarantee as long as the premiums are paid the policy will not lapse. The newest form of universal life insurance is the indexed universal life policy which has performance tied to the S&P Index, Russell Index and the Dow Jones. In a down market you usually have no gain but you have no losses to the policy either. If the market is up you can have a gain but it is limited. If the index market takes a 30% loss then you have what we call the floor which is 0 which means you have no loss but there is no gain. Some insurers will still give as much as 3% gain added to you policy even in a down market. If the market goes up 30% then you can share in the gain but you are capped so you may only get 6% of the gain and this will depend on the cap rate and the participation rate. The cap rate helps the insurer because they are taking a risk that if the market goes down the insured will not suffer and if the market goes up the insured can share in a percentage of the gains. Indexed universal life policies also have cash values which can be borrowed. The best way to look at the difference in cash values is to have your insurance agent show you illustrations so you can see what fits you investment profile. The index universal life policy has a design which is beneficial to the consumer and the insurer and can be a viable tool in your total investments.

Tom Rawls Jr. CLU, CHFC, RHU, REBC, CASL, CAP is an insurance advisor with over 24 years of experience, who takes the time to understand his clients unique desires and goals. The Whole Life Advisor Insurance Brokerage Team specializes in Life, Disability, Long Term Care, and Annuities


cccccccc